A short sale is a sale of real estate in which the proceeds from the sale fall short of the balance owed on a loan secured by the property sold. In a short sale, the bank or mortgage lender agrees to discount a loan balance due to an economic or financial hardship on the part of the mortgagor. This negotiation is all done through communication with a bank's loss mitigation or workout department. The home owner/debtor sells the mortgaged property for less than the outstanding balance of the loan, and turns over the proceeds of the sale to the lender, sometimes (but not always) in full satisfaction of the debt. In such instances, the lender would have the right to approve or disapprove of a proposed sale.
A short sale typically is executed to prevent a home foreclosure. Often a bank will allow a short sale if they believe that it will result in a smaller financial loss than foreclosing. For the home owner, advantages include avoidance of a foreclosure on their credit history and partial control of the monetary deficiency.
Short sale is not the guarantee that the bank will accept the offering price on the property and can take anywhere from 90-120 days to receive an answer from the lender whether they are or are not accepting the deal.
If you have any further questions, please don't hesitate to contact me directly.
Saturday, February 21, 2009


Friday, February 20, 2009
STIMULUS BILL - $8,000 FOR HOMEBUYERS
Final score: $8,000 for homebuyers
First-time purchasers get a tax credit windfall if they buy before December.
By Les Christie, CNNMoney.com staff writer
February 16, 2009: 5:38 PM ET
NEW YORK (CNNMoney.com) -- There's a nice windfall for some homebuyers in the economic stimulus bill awaiting President Obama's signature on Tuesday. First-time buyers can claim a credit worth $8,000 - or 10% of the home's value, whichever is less - on their 2008 or 2009 taxes.
A big plus is that the credit is refundable, meaning tax filers see a refund of the full $8,000 even if their total tax bill - the amount of withholding they paid during the year plus anything extra they had to pony up when they filed their returns - was less than that amount. But there has been a lot of confusion over this provision. Adam Billings of Knoxville, Tenn. wrote to CNNMoney.com asking:
"I will qualify as a first-time home buyer, and I am currently set to get a small tax refund for 2008. Does that mean if I purchased now that I would get an extra $8,000 added on top of my current refund?"
Not exactly. Billings won't get $8,000 on top of his current refund, but he would turn that small refund into a much larger one. If his total tax liability came to $6,000, but he had $7,000 withheld from his payroll, he would normally receive a $1,000 refund. With this credit, his refund would total $8,000. If the credit were non-refundable, as was originally proposed in the Senate version of the stimulus package, he would have only received $6,000, or the total amount he paid in.
To qualify for the credit, the purchase must be made between Jan. 1, 2009 and Nov. 30, 2009. Buyers may not have owned a home for the past three years to qualify as "first time" buyer. They must also live in the house for at least three years, or they will be obligated to pay back the credit.
Additionally, there are income restrictions: To qualify, buyers must make less than $75,000 for singles or $150,000 for couples. (Higher-income buyers may receive a partial credit.)
Applying for the credit will be easy - or at least as easy as doing your income taxes. Just claim it on your return. No other forms or papers have to be filed. Taxpayers who have already completed their returns can file amended returns for 2008 to claim the credit.
Lukewarm reception
The housing industry is somewhat pleased with the result because the stimulus plan improves on the current $7,500 tax credit, which was passed in July and was more of a low-interest loan than an actual credit. But the industry was also disappointed that Congress did not go even further and adopt the Senate's proposal of a $15,000 non-refundable credit for all homebuyers.
"[The Senate version] would have done a lot more to turn around the housing market," said Bernard Markstein, an economist and director of forecasting for the National Association of Homebuilders (NAHB). "We have a lot of reports of people who would be coming off the fence because of it."
Even so, the $8,000 credit will bring an additional 300,000 new homebuyers into the market, according to estimates by Lawrence Yun, chief economist for the National Association of Realtors.
The credit could also create a domino effect, he said, because each first-time homebuyer sale will lead to two more trade-up transactions down the line. "I think there are many homeowners who would be trading-up but they have had no buyers for their own homes," Yun said.
Who won't benefit, according to Mark Goldman, a real estate lecturer at San Diego State University, are those first-time homebuyers struggling to come up with down payments. The credit does not help get them over that hurdle - they still have to close the sale before claiming the bonus.
Instead, many may look at the tax credit as a discount on the home price, according to Yun. A $100,000 purchase effectively becomes a $92,000 one. That can reassure buyers apprehensive about purchasing and then watching prices continue falling, he added.
And it provides a nice nest egg for the often-difficult early years of homeownership, when unexpected repairs and expenses often crop up. Recipients could also use the money to buy new stuff for their home - a lawnmower, a rug, a sofa - and, in that way, help stimulate the economy.
Saturday, February 7, 2009
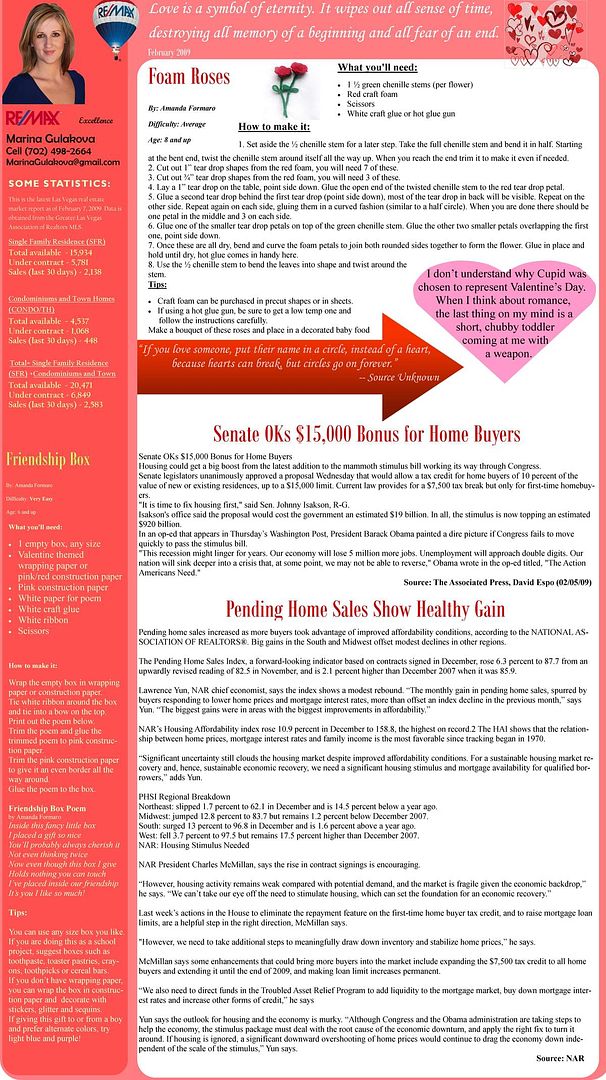
February Newsletter
Friday, February 6, 2009
WHAT IS BANK-OWNED/ REO/ FORECLOSED PROPERTY?
What is an REO? REO means "real estate owned" and is a term used by the financial industry to describe properties (assets) that a financial institution has possessed by foreclosure, a deed-in-lieu of foreclosure, or other means. REO properties are also called "bank owned" or "corporate owned" because the owner of record is an institution instead of a natural person.
Is an REO property a "better" deal that other properties on the market? Only a willing buyer and seller determine the purchase price of a property. Just like other resale homes, REO properties have different amenities and are in various stages of age and repair. All of these factors influence the price that a buyer and seller are willing to agree on.
What kind of financing is available for an REO property? It is a sad truth that some properties have been vandalized. Certain loan products (for example, FHA loans) are not available for properties that do not have certain appliances, floor coverings and utilities. Check with your loan provider for complete and up-to-date details about your loan requirements.
How will you know if you are competing against other potential buyers? Listing agents may or may not have authority from the seller to disclose multiple offers. The REALTOR Code of Ethics requires a listing agent to have the seller's approval before disclosing the existence of other unaccepted offers on the property. A seller may respond to numerous offers with a "multiple counteroffer." This document alerts two or more buyers that they are in a competitive situation.
Can you choose the title company? Typically, the banks and lenders who have foreclosed on these homes have established business relationships with title companies, who often act as the escrow holder. Even before a home is put on the market, the title company may have opened a file and started its research on the title. Under federal law, a seller cannot require a buyer to purchase title insurance from a particular company, but if the seller is paying for the buyer's title policy then the seller may choose the title company. For a consumer's guide to title insurance, go to
What kind of disclosures will you receive from the seller? Federal and state laws require a seller to make certain disclosures to a prospective purchaser. The "Residential Disclosure Guide" provided by the Real Estate agent outlines these disclosures. Some disclosures, such as the Seller's Real Property Disclosure, can be waived according to state law. Others, such as the Common Interest Community resale package, cannot.If you close escrow without receiving a required disclosure, your right to sue for such a failure may be affected. If you have any concerns, consult with legal counsel prior to closing escrow.
Will the seller pay for repairs? A typical REO is sold "as is," meaning that the seller will not do repairs on the property or provide funds at closing for repairs. However, buyer's agents may still ask for repairs and attempt to negotiate that point. As the adage goes, "you won't know unless you ask." You may not receive multiple keys or garage openers.
Should you have home inspection? Although an REO seller may not provide a property disclosure or make repairs, the buyer is still entitled to have an inspector review the home. Buyers should consult whatever qualified professionals (such as home inspectors, mold inspectors, pest/termite inspectors) they desire to determine the state of the property and whether the property meets their needs.
This is general information and is not intended to provide information or advice on any specific transaction. Parties to any real estate transaction should seek competent legal and/or tax counsel to determine the legal, credit and tax consequences of buying or selling a home.
Wednesday, December 10, 2008
LOAN MODIFICATIONS ARE NOT WORKING!
According to the Thrift Supervision National Housing Forum that was held on December 8, the re-default rate of modified loans (which represent about 60% of all the loans), loans modified in the first quarter of this year after 3 months only nearly 36% of them defaulted again by being past 30 days late; after 6 months the re-default rate is 53% and after 8 months, it’s 58%. For the second quarter, the re-default rates are about the same. More than half of the modified loans are defaulting again, I believe it is an indication that loan modification is not working. Whether it’s due to the lack of principle reduction or simply economy in crisis, we wouldn’t be able to determine. Most likely, all of the above.
Source: CNBC.com
http://www.cnbc.com/id/15840232?video=955168734
Source: CNBC.com
http://www.cnbc.com/id/15840232?video=955168734
Wednesday, November 19, 2008
HOW TO BUY A HOUSE WITH NO DOWNPAYMENT
How To Buy A Home With Zero Down
Las Vegas: A new home ownership program allows qualified buyers to buy a home with absolutely no down payment.
You may have owned a home before and are presently renting, or maybe you are a first time homebuyer and need a way to break into the housing market but are holding back because you think you require $10.000, $20.000 or even more for a down payment.
Well regardless of your present situation, if you want to get into, or re-enter the housing market without having to make a cash down payment, this new program may be just what you're looking for. Why pay your landlord's mortgage when you can be building your own equity.
Industry insiders have prepared a new special report entitled, "How to Buy a Home With Zero Down' which reveals how this new and innovative program can get you into the housing market immediately and with no down payment.
To get your FREE copy today visit
www.LVRealDeal.com
or call 877-583-1181 ID#712
FHA is changing the maximum amount of the loan!
Starting January 1, 2009 the max FHA loan limit for Clark County is $287,500.00. If you are shopping for a home using FHA financing that will exceed this limit we need to get the offers in place NOW because we need to LOCK the loan by 12/10/2008 and FUND by 12/31/2008 to be able to get you the perfect home. CALL ME!
Monday, November 3, 2008
*****FORECLOSURES*************************
DISTRESS SALE
Bank Foreclosures
FREE list of Bank-owned properties
Receive a FREE computerized daily update
Visit: www.LVRealDeal.com to find out more
Bank Foreclosures
FREE list of Bank-owned properties
Receive a FREE computerized daily update
Visit: www.LVRealDeal.com to find out more
| | |||
Sunday, November 2, 2008
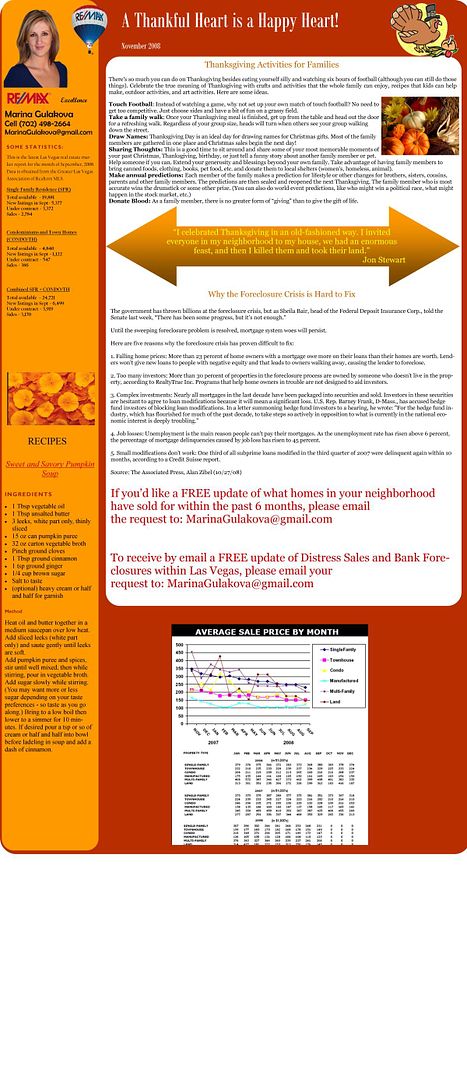
November 2008 update
Sunday, October 12, 2008
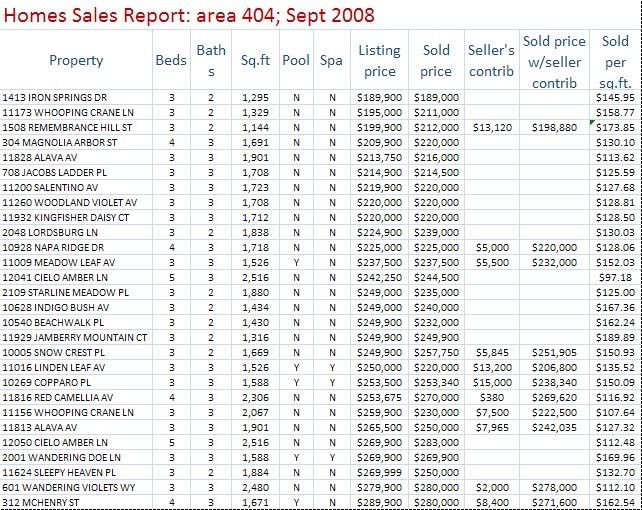
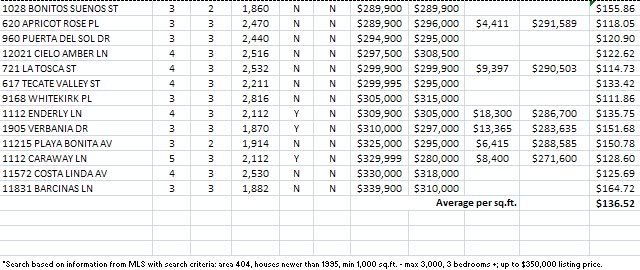
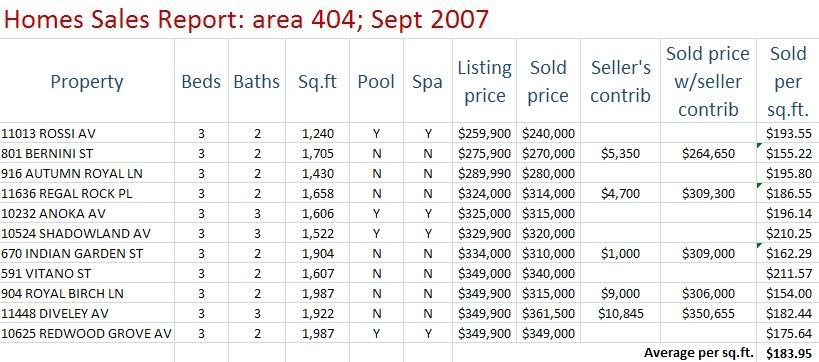
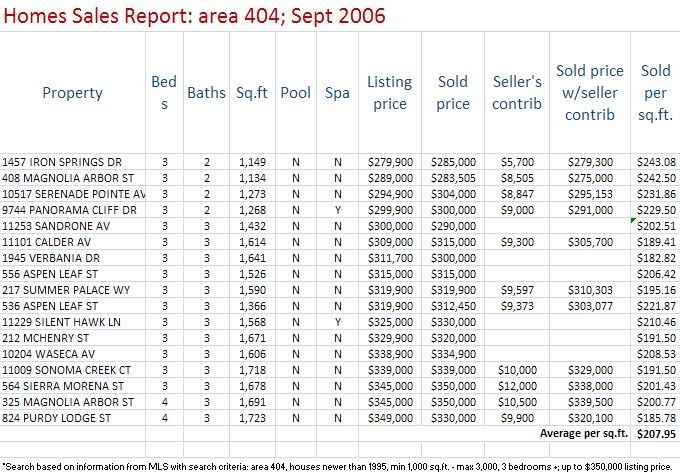
SALES TRENDS in part of the Summerlin Area - September '08, '07 & '06
Here I compared the average sales for North Summerlin area (404) for September 2008, 2007 & 2006. As you can see, this year the average price per square foot dropped to $137 compared with September 2007 - $186 (see below) and September 2006 - $208 (see below).
If you'd like to find out what's been happening to the pricing in your neighborhood, please email me with request: MarinaGulakova@gmail.com

If you'd like to find out what's been happening to the pricing in your neighborhood, please email me with request: MarinaGulakova@gmail.com
Tuesday, October 7, 2008


Wednesday, October 1, 2008

Tuesday, September 30, 2008
100% financing is back! It’s legitimate, it’s helpful, and it’s back.
So, we have a 100% financing program back!!! It’s legitimate, it’s helpful, and it’s back.
Since the government decided to “kill” even further the real estate business with the cancellation of Nehemiah program, we thought that a big portion of folks won’t be able to afford homes any longer. Some may argue that if people can’t afford even 3% down payment (the requirement for FHA loans) and require assistance on paying the closing costs as well, then they shouldn’t be buying a home to begin with as they obviously can’t afford it! Well, I think it’s just one of the ways of leveraging available cash: the less cash you put towards the purchase, the more you have left for renovating the place or acquiring more properties.
It works simply as any other FHA program would. This 100% program allows you to borrow additional money to cover your down payment and /or closing costs at 2% above first mortgage rate up to $10,000 max.
Let’s look at the example:
Say, you want to buy a property for $165,000.
Down payment of 3% required : $4,950 (although the new law states that the down payment should be at least 3.5%, some lenders are still lending with 3% down payment only)
Closing costs: $4,950
Inspection and appraisal: $350 + $250 = $600 (we are assuming the appraisal is not reimbursed by the seller)
Total cash required: $10,500 needed to purchase - Down payment and closing costs assistance of up to $9,900 = $600
Financing:
$165,000 – $4,950 down payment = $160,050; this is the amount that needs to be financed under standard FHA program. The other $9,900 (for down payment and/or closing costs) will be financed for 20 years only and at a rate 2% higher than your APR.
****Let’s assume the APR rate is 6.5%, annual property taxes are $2,200 (I know it seems high, but currently it’s one of the problems with properties in LV – the prices have fallen, but the property taxes were assessed based on previous values of the properties which were higher; eventually, the property taxes should come down significantly or you can appeal to have your property taxes reassessed), the loan term is 30 years fixed.
Your payments for loans would be: $1,012 (for 1st loan) + $86 (2nd loan) = $1,098
Plus taxes of $183, your monthly payment is $1,281. We should also add HOA fee to this equation, however, the HOA fees vary greatly. Let’s assume the HOA in this case is $30.
THE TOTAL PAYMENT IS: $1,311.
This is not bad, as the rent for such a home would be about $1,300 - $1,500/m.
This program allows you to have little or no cash upfront.
If you’d like more information on this program, let me know!
****Some restrictions and limitations might apply.
Wednesday, September 17, 2008

Sunday, September 7, 2008

Saturday, August 16, 2008

Wednesday, August 6, 2008
Thursday, July 24, 2008
Subscribe to:
Posts (Atom)


 Posts